This microsite exists to explain the money side of practice at the self-employed Bar in plain English: clearly, accurately, and without ever crossing into advice you have not asked for.
The self-employed Bar sits in an unusual financial position. Income is lumpy and arrives late; there is no employer quietly funding a pension, no sick pay, no death-in-service scheme. A large share of what lands in the account is money that is not yours to spend. And the rules that govern all of this (Making Tax Digital, the basis period reform, the annual allowance taper, the coming changes to inheritance tax on pensions) are moving quickly.
Most general financial content is written for employees. It assumes a steady salary, a workplace pension and a fixed retirement date. Very little of it is written with a barrister's cash-flow shape, aged debt and career transitions in mind. This site tries to close that gap.
Altor for the Bar and Altor
The site is published by Altor for the Bar, an initiative from Altor, a firm that advises members of the Bar day to day. That practical, day-to-day contact with counsel is what shapes the material: the questions here are the ones that actually come up in chambers, not the ones a generic guide assumes.
Who you'd be dealing with
Altor is deliberately small. If you get in touch, you deal with one of these two, not a relationship manager who passes you on.
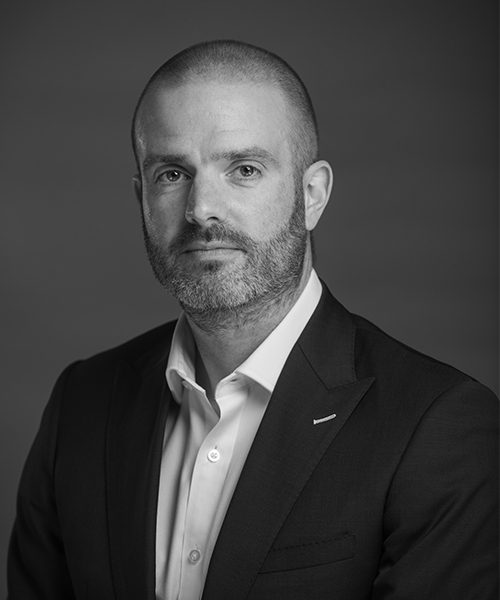
Matt Pitcher
Managing Partner · Chartered Financial Planner
Matt began as an independent adviser in 2001 at Towry Law, rising to become one of only four Executive Partners nationally. When Towry was acquired by the private equity house Permira in 2016, he left to found Altor, on the straightforward view that charging clients a percentage of their wealth was the wrong way round.
He has advised members of the Bar and their families for many years, including several across more than one generation.
Outside work most of his time goes to his family, and what is left to supporting the England rugby team, with results that vary.
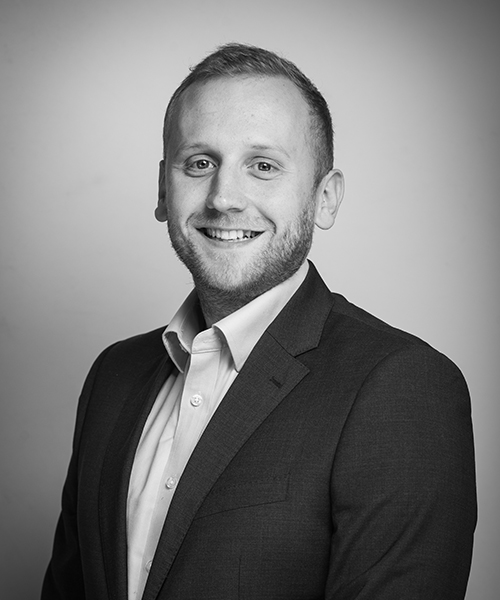
Lee Harman
Financial Planner · Chartered Financial Planner
Lee trained at the London advice firm Saunderson House, became an adviser in 2018 and achieved Chartered status the following year. He left after a takeover, looking for a firm whose charging model matched his own view of how clients ought to be treated.
He travels as much as work allows, and follows football, cricket and motor racing with roughly equal commitment.
I unhesitatingly recommend Matt Pitcher of Altor Wealth Management as a financial adviser. He has for some time been an adviser to my entire family, who, not surprisingly, have different financial positions and needs. He is as honest as the day is long, highly competent, the giver of wise advice in relation to how matters should be structured, and a pleasure to deal with.
An arbitrator at Brick Court Chambers
One client's view of the service they received. It is not a guarantee of the service any other client will receive, and it says nothing about investment returns.
The line we hold
Everything on this microsite is generic education: how the mechanics currently work, and what may matter in which circumstances. Nothing here is personal financial advice, and nothing here is a recommendation to buy, sell or hold any particular product or investment. Personal advice only happens in a personal conversation, where your full circumstances are known.
If you would like to talk
The most useful next step is usually a short, no-obligation conversation with an adviser who works with members of the Bar.